


Think of the economy as a pie. We all bake it together, through our working lives. Then, we have to figure out how to slice it. How much should go to owners — shareholders, landlords, bosses, and so on — and how much should go to workers?
The proportion that goes to workers is called labor’s share of income. And it just hit an all-time low.
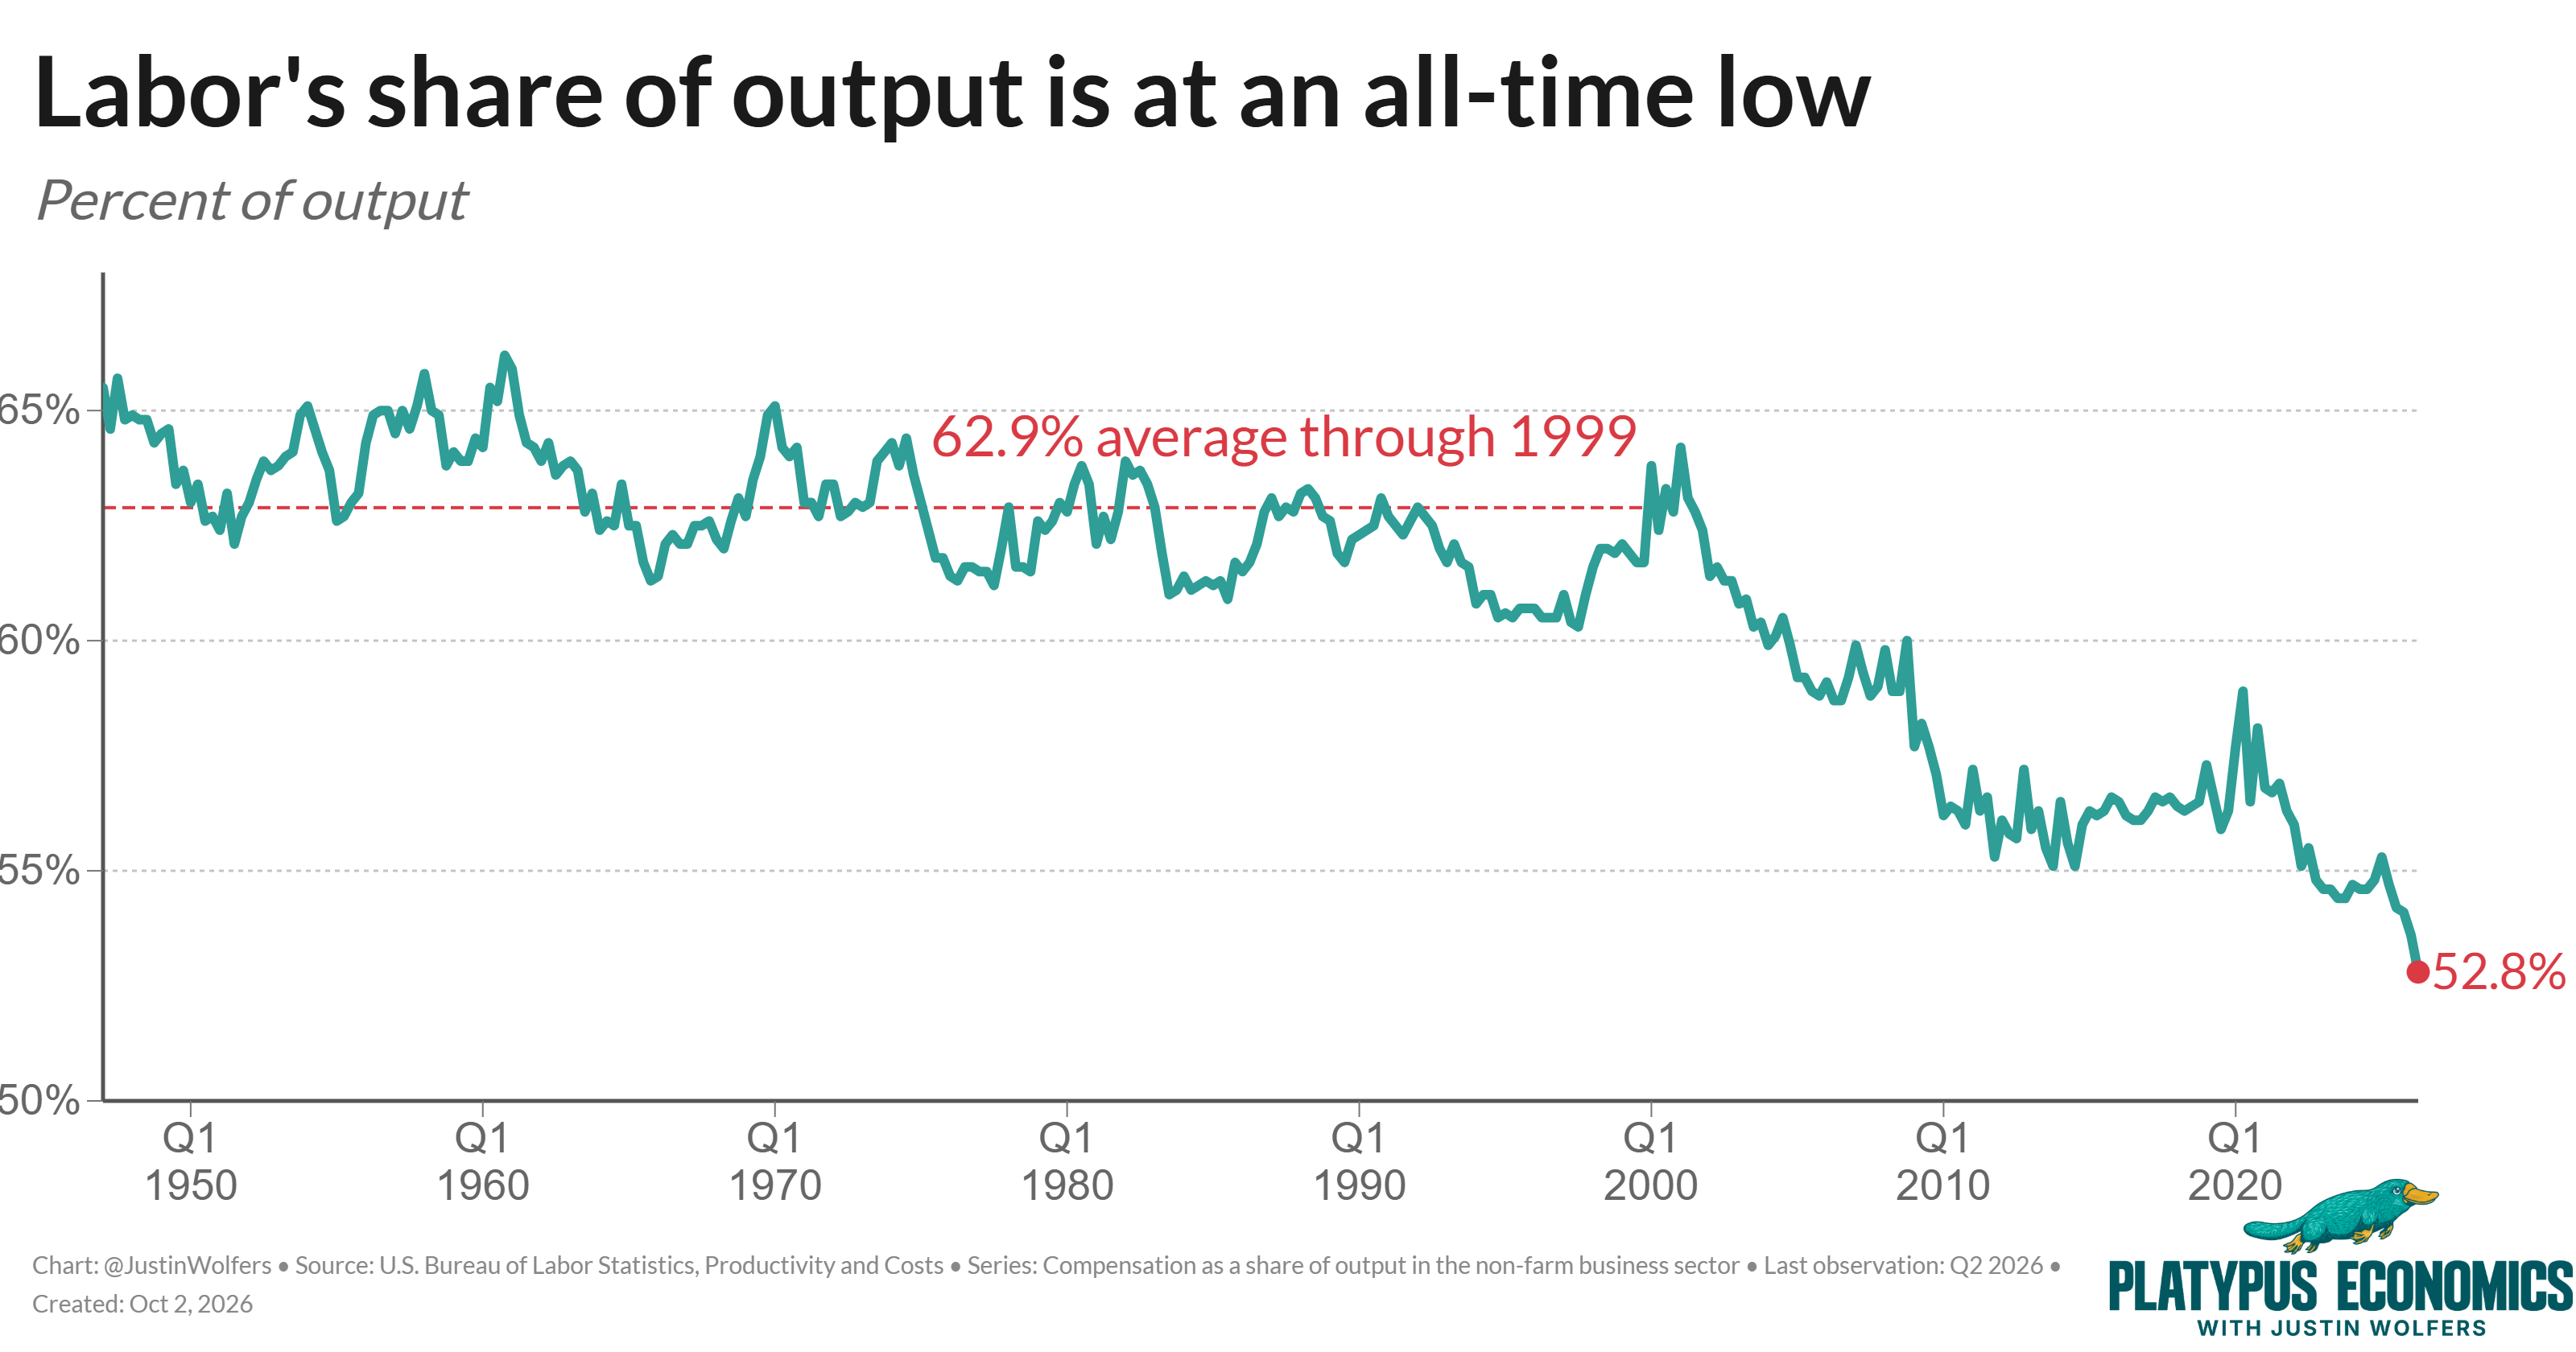
If you take the entire U.S. national income, a larger share than ever of everything we earn as a nation goes to owners. Put differently, workers are seeing a smaller share of the general prosperity than ever before.
We dug into the why of all this a few weeks ago.
Is this something to worry about?
That’s what Stacey Vanek Smith asked me at our first-ever live Off the Clock podcast. This was at Stanford’s Initiative for Financial Decision-Making. Stacey wasn’t being glib. She’s an amazing financial journalist, so she has to ask the hard questions (and she works at Bloomberg — someone has to stand up for capital).
You can watch the episode here:
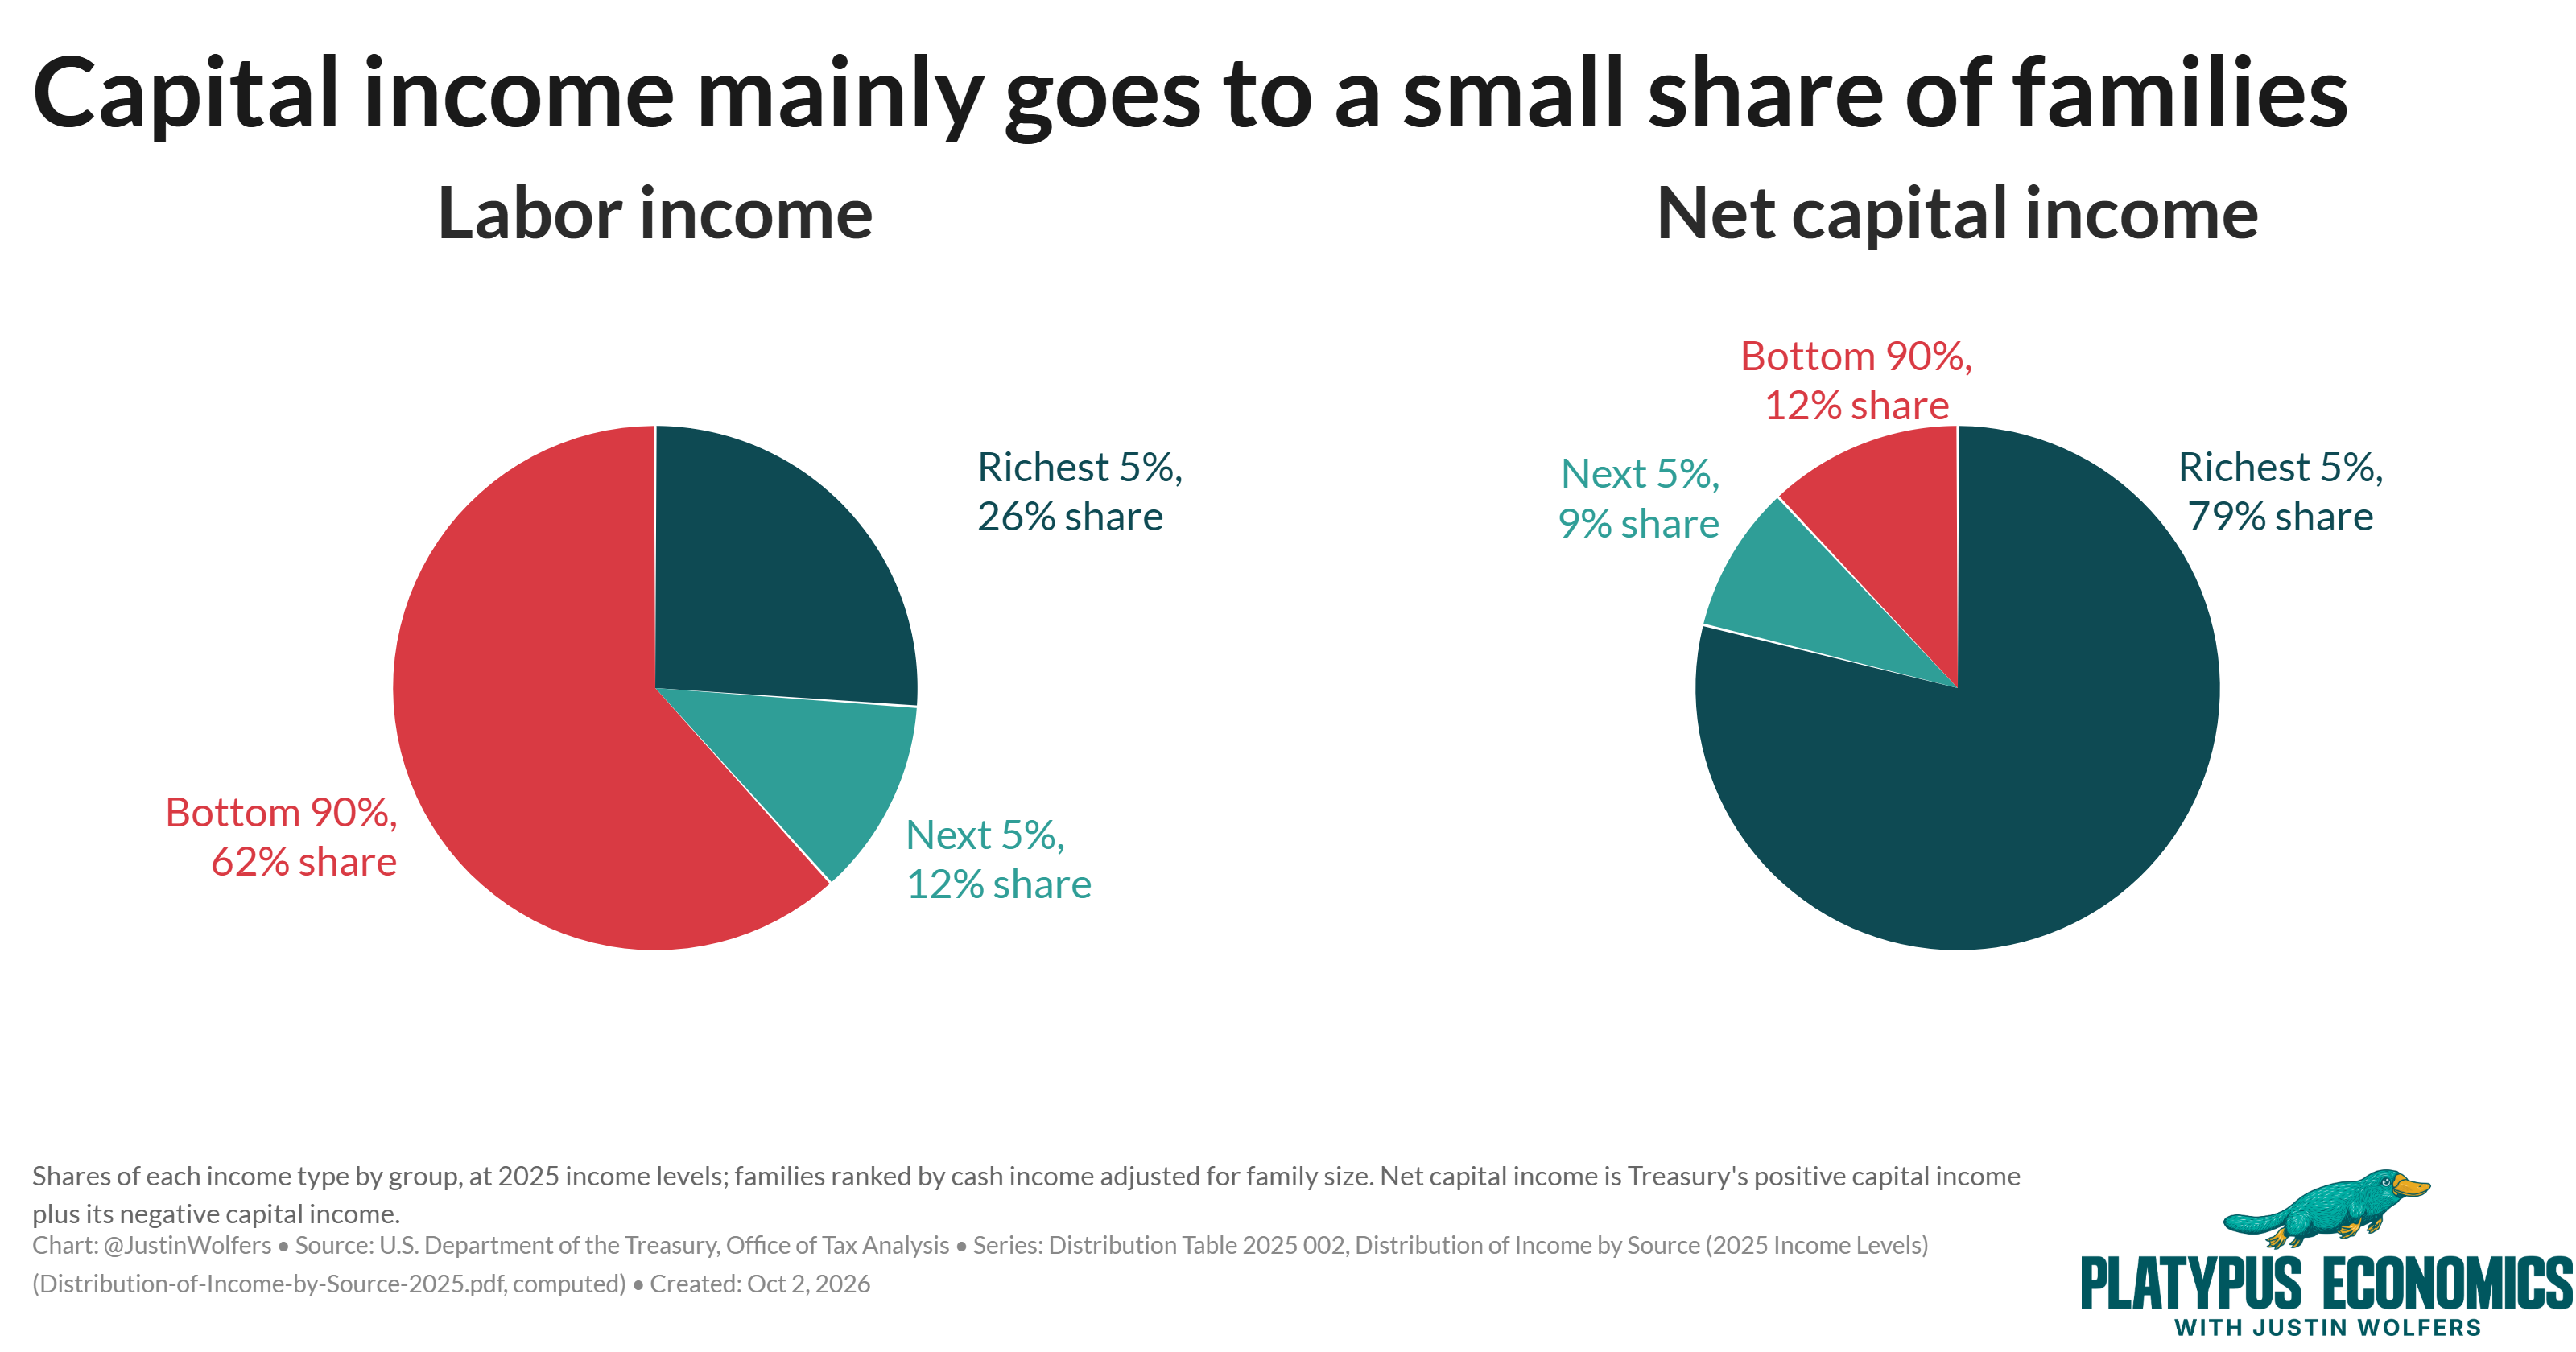
Let me preview my answer in text form. For most families, they get most of their money from a paycheck. It’s how they pay their bills and survive. By contrast, capital is highly concentrated. When the workers’ part of the pie shrinks, most people’s slice shrinks with it.
Stacey brought her own illustration of this. It came from The Simpsons.
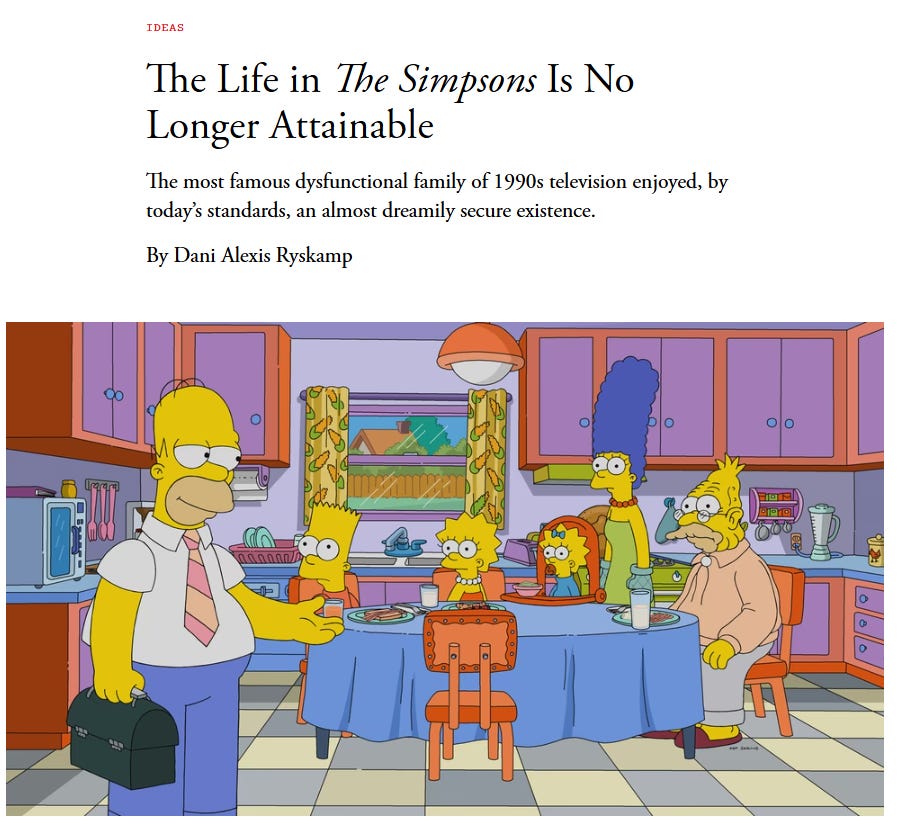
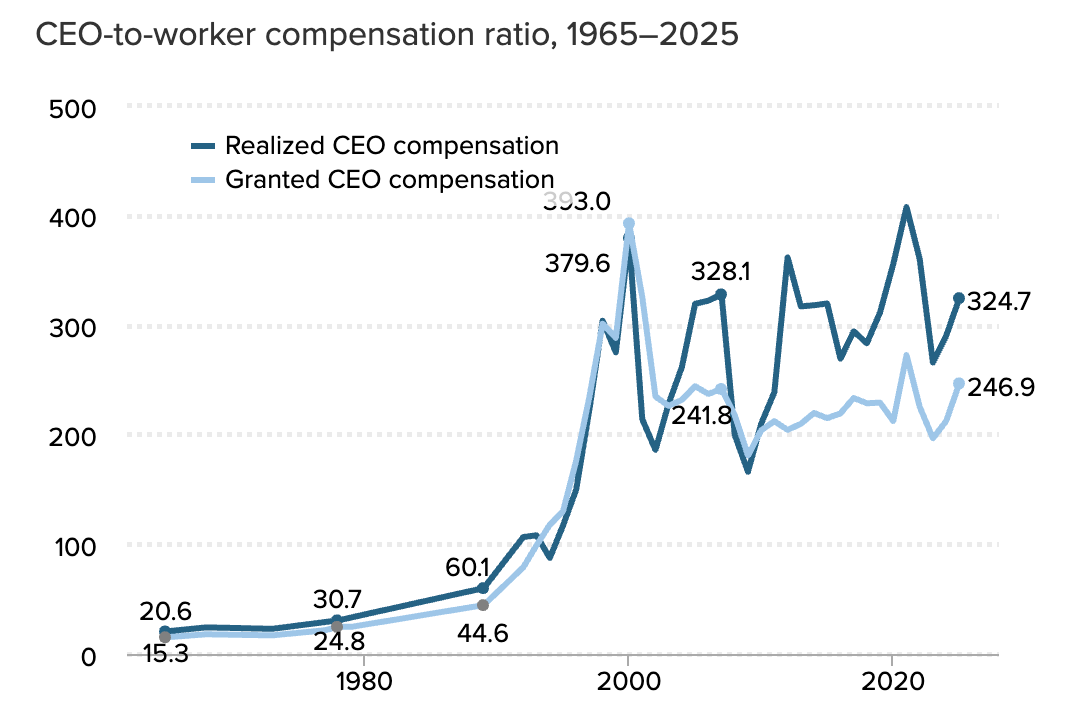
Some background: An Atlantic writer named Dani Alexis Ryskamp went through old episodes to work out how much Homer made at the nuclear power plant. In today’s dollars, it comes out to about $55,000. When the show started, CEOs earned about 60 times what their average worker earned. Now they make 325 times as much. Call this the Mr. Burns-Homer Simpson ratio.
Stacey pushed back further. What’s actually wrong with concentrated wealth? Elon Musk is the first trillionaire. Love him or hate him, he has created a lot of jobs. Stacey pointed out that’s more economic good than she would have done with the money (though I’m not sure that’s true — she would have created more public radio stations, which sounds like a pretty good world).
What a trillion dollars can buy
When you ask economists why billionaires are a problem, we often struggle. There’s an easy answer, which is that more money in the hands of the middle class instead of the ultra-wealthy means more joy. If Homer got a little more, it would make a much bigger difference to his life than if Mr. Burns got that money instead. But a direct answer about billionaires is harder.
Take Elon Musk. In the last election, he gave $250 million to one side of politics. That side subsequently won the election by 230,000 votes in three key states — Michigan, Pennsylvania, and Wisconsin. Even if he spent $1,000 to secure each vote, that was enough that his dollars made all the difference. And the bloke has a trillion dollars, so buying this election didn’t cost him much of his wealth. Indeed, if he wanted to, he could afford to buy 3,999 more U.S. elections.
Stacey wasn’t fully convinced. She doesn’t believe that you can buy a vote. (Every political candidate who has ever asked for a donation disagrees.) But she accepted the broader point: Concentration of wealth is also concentration of power. I’m not sure that’s good for capitalism, and I’m quite sure it’s not good for democracy.
The thing about that level of wealth is that there isn’t much else it gets you. With $99 million, I could buy anything I wanted: fancy clothes, gorgeous cars, that small private jet with a Platypus on the side.
The next part I may have put too provocatively, but I think it’s part of the struggle we have with this question. If there’s nothing left to buy above $100 million, why let anyone get there? Once you’ve got that kind of coin, the only extra thing you can buy with that extra money is power.
Stacey said that was the kind of claim that got dangerous fast. Too many restrictions on the rich can simply push them to move somewhere friendlier; and there are plenty of places that would like to have them. That’s a fair point and an argument for another day. But I’ll say this: if I were the captain of the billionaires’ club, I’d be calling an emergency meeting right now.
A few other hot topics
We covered lots of other topics during our live show. We talked about AI and labor via the “StaceyBot 2000,” which is a robot that can do Stacey’s work. Does it make her better or worse off? I explained why Keynes was right about labor and wrong about how productivity would mean we’d all work 15 hour weeks. (If you’ve never read Economic Possibilities for our Grandchildren, let me give you the link, now.)
And in a lighter moment, Stacey took the great iced-coffee-in-job-interviews debate and made it all serious again, arguing that the very fact of this debate reveals something about the difficult job market facing young people.
Thanks to Annamaria Lusardi and Stanford for having us. This experience got me fired up about so much, including the idea of doing more live shows.
If you’d like to see an Off the Clock near you, or if you’ve got a question you’d like Stacey and me to answer, please let me know in the comments.
The biggest problems are that: (1) with Citizens United it’s a huge threat to democracy, as Elon can give more than all the working class people in most states and Zuckface & Elon’s sociopathic media platforms allow fake Russian accounts, massive slander, and AI generated fake video to poison our politics
(2) It’s a huge threat to our children’s and our mental health as the tech bros do nothing in the face of evidence that their platforms and AI bots inflict mental health issues on our kids and even encourage them to commit suicide, but they have so much money neither party can just go after them for fear of #1
(3) it’s a fundamental threat to our national security. With carried interest loophole, buy, borrow & die smartasset.com/investing/buy-borrow-die-how-the-rich-avoid-taxes, Maltese IRAs www.npr.org/2026/05/27/nx-s1-5835164/malta-tax-evasion-avoidance-loophole?, and countless other loopholes the rich lobby for constantly combined with Trump slashing IRS audit staff, more of our income is shifting to people who don’t pay taxes as our debt and interest payments spiral to banana republic levels. Combined with Congress rewarding high cost defense contractors who prioritize spreading subcontracts across key congressional districts and maximizing prices, our debt situation threatened our ability to keep up with China’s much lower cost per unit military growth.
The United States has transitioned to a winner-take-all, non-linear economy—characterized by network effects, extreme wealth concentration, and "superstar" market dominance—the traditional Economics 101 (Econ 101) curriculum becomes significantly less relevant for describing the modern world, though it remains essential as a foundational toolkit. While the core analytical methods of Econ 101 still hold value, its foundational assumptions often fail to capture the dynamics of a non-linear economic reality.
Standard introductory economics is heavily built on 19th and 20th-century models of perfect competition and linear returns. A non-linear, winner-take-all economy breaks these models in several fundamental ways: Econ 101 teaches that as businesses grow, they face diminishing returns (higher costs and lower efficiency). In the digital and non-linear economy, tech giants and platform monopolies experience increasing returns to scale. The marginal cost of replicating software or a digital service is virtually zero, allowing a single dominant player to scale infinitely and crush competition. Traditional curriculum suggests that workers are paid based on their marginal productivity (the specific value they add). In a winner-take-all system, network effects dictate success. A software engineer at a trillion-dollar company isn't necessarily thousands of times more "productive" than one at a failed startup; rather, they are leveraging a non-linear platform that scales their output globally. Econ 101 spends a massive amount of time on perfect competition—where many small firms sell identical products and have no market power. Today’s dominant markets (search engines, social media, e-commerce, operating systems) naturally trend toward monopoly or duopoly, making perfect competition an increasingly abstract fantasy rather than a useful baseline. Linear economics assumes markets naturally self-correct toward a stable equilibrium. Non-linear economics is defined by path dependency and "tipping points," where early, often accidental advantages lock in a winner permanently, preventing the market from correcting itself.
Despite these massive blind spots, the curriculum cannot be discarded entirely. It serves as a necessary scaffold for higher-level economic thought: You cannot fully grasp why a non-linear market is "failing" or operating differently without first understanding the baseline mechanics of supply, demand, opportunity cost, and scarcity. The core Econ 101 maxim that "people respond to incentives" remains universally true. The incentives in a winner-take-all economy just lead to different behaviors (e.g., companies burning billions in venture capital to achieve monopoly status rather than trying to turn an immediate profit). While the tech and corporate landscape is non-linear, large swaths of the everyday economy—like local restaurants, construction, hair salons, and physical retail—still operate largely under standard, linear Econ 101 principles of supply, demand, and localized competition.
The standard Econ 101 curriculum is no longer adequate as a standalone map of the macroeconomic landscape. It acts more like learning Newtonian physics: it works perfectly well for basic, everyday objects, but completely breaks down when you try to apply it to the "quantum realm" of modern, digital, network-driven economies. For the curriculum to remain truly relevant, universities must rapidly shift their focus away from perfect competition models and integrate concepts of information economics, game theory, network externalities, and market power much earlier in the educational track.