

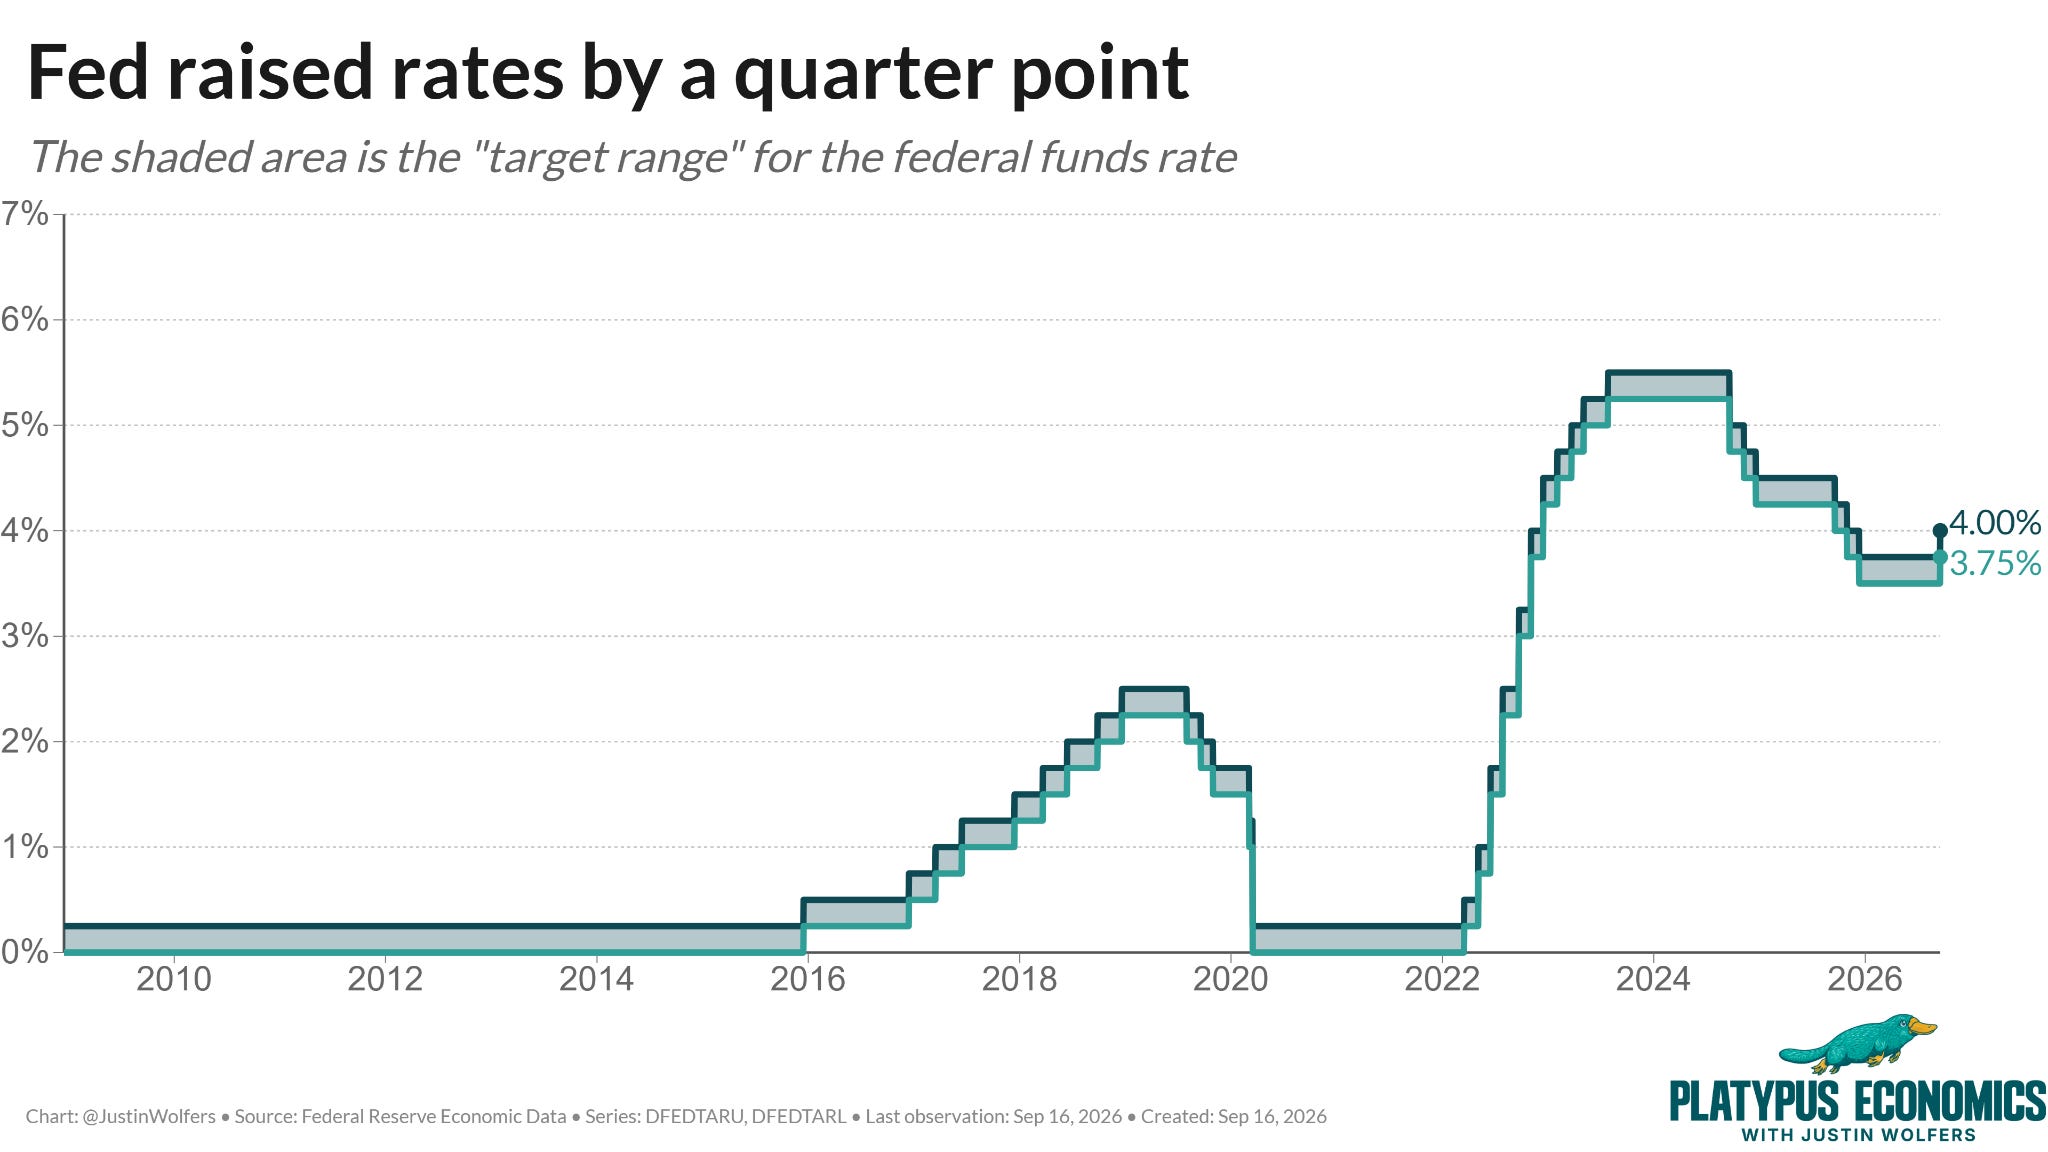
The Federal Reserve just raised interest rates by one quarter of a percentage point. This is the first rate rise since 2023. Higher rates in the face of inflation normally isn’t particularly notable. But this rate rise occurred in direct opposition to demands President Trump made of his handpicked new Chair that the Fed lower rates. That chair, Kevin Warsh, held his ground.
Today, Warsh delivered a simple message: Inflation is too high, and it’s been too high for too long.
This decision was, in many respects, entirely predictable. And entirely predicted. In fact, there’s a market where you can bet on what the Fed’s going to do next. It’s called Federal Funds Futures. And as of this morning, it said that there was a 92% chance the Fed would do this.
Which raises a question: What were markets worried about in the other 8%?
What actually, literally just happened
The Fed raised its main policy rate, the federal funds rate, by a quarter of a percentage point. This is an aside, but the Fed does a thing I kind of hate where it doesn’t announce one interest rate. Instead, it announces a range. It bugs me simply because it adds yet another complication to how we discuss the Fed’s choices. Its target is now for the Federal Funds rate to be somewhere between 3.75% and 4%.
The most important detail is that the vote was unanimous. All 12 voting members of the Federal Open Market Committee backed the hike. That includes Warsh, who did this in spite of the bloke who appointed him basically demanding his lower rates or else.
Normally you might expect a policy decision that was widely anticipated to be a yawn-fest. But this one drew a lot of interest, and caused some pretty sharp market movements. That’s because we have a new Fed chair, and none of us really know who he is. And today gave us some important insight into that.
So: let me introduce you to three Kevins.
Kevin No. 1: Sock Puppet Kevin
A lot of people feared that our new Fed Chair was Sock Puppet Kevin. That, even though the Fed is supposed to be impartial and nonpartisan, the president had succeeded in bringing someone on who would simply do his bidding (even if it didn’t make sense for the American economy).
That’s not a paranoid fear. We’ve watched it happen throughout the federal government, including at agencies that are supposed to be independent. The Department of Justice leaps to mind.
Sock Puppet Kevin would give the president the rates the president wants, whether or not they made good sense.
Today, the president wanted lower rates. Warsh voted for higher rates.
So he’s not Sock Puppet Kevin. That’s very good news.
But that still leaves two possibilities.
Which Kevin is behind the next door?
We’re still getting to know Warsh. So even with this hike, it’s possible that he might be Beige Kevin.
Beige Kevin is Kevin the economist. He’s like the other members of the committee, and he does roughly what most economists think the Fed should do. On this view, Warsh voted with his colleagues because that’s what beige people do. They go along to get along.
The third possibility is Hawkish Kevin.
A quick bit of jargon: In Fed-speak, a hawk is someone who always sees inflation just around the corner, and who is quick on the trigger to raise rates at any hint of it. The opposite is a dove: someone more focused on unemployment, and less on inflation.
Why do we think Warsh might be Hawkish Kevin? Because we’ve seen Hawkish Kevin before. Warsh served on the Fed Board from 2006 to 2011, during a stretch when inflation was very low. Throughout that period, he kept warning that inflation was just around the corner. And throughout a period when the economy clearly needed low interest rates, he kept pushing for higher ones.
Today’s vote was something that both Beige Kevin and Hawkish Kevin would approve of. To tell them apart, you have to watch what happened next.
Silent Kevin moves the markets
When the Fed announced its decision at 2 p.m., financial markets didn’t react. Perhaps the tiniest blip, but really, nothing. Markets were pretty confident — 92% sure — that a quarter point rate hike was on the cards. As such, there was not much news to price in.
Then at 2:30 p.m., Warsh stepped behind the podium for a press conference.
Here I have to introduce my favorite Kevin — or at least my favorite nickname. Warsh has said he doesn’t like “forward guidance,” more jargon for the Fed’s habit of telling markets where rates are headed. He wants people listening to the economic indicators (not to the Fed chair). So I call him Silent Kevin.
Silent Kevin may think he doesn’t want to move markets. But, when he speaks, markets respond. Once he got behind that podium, stocks fell sharply.
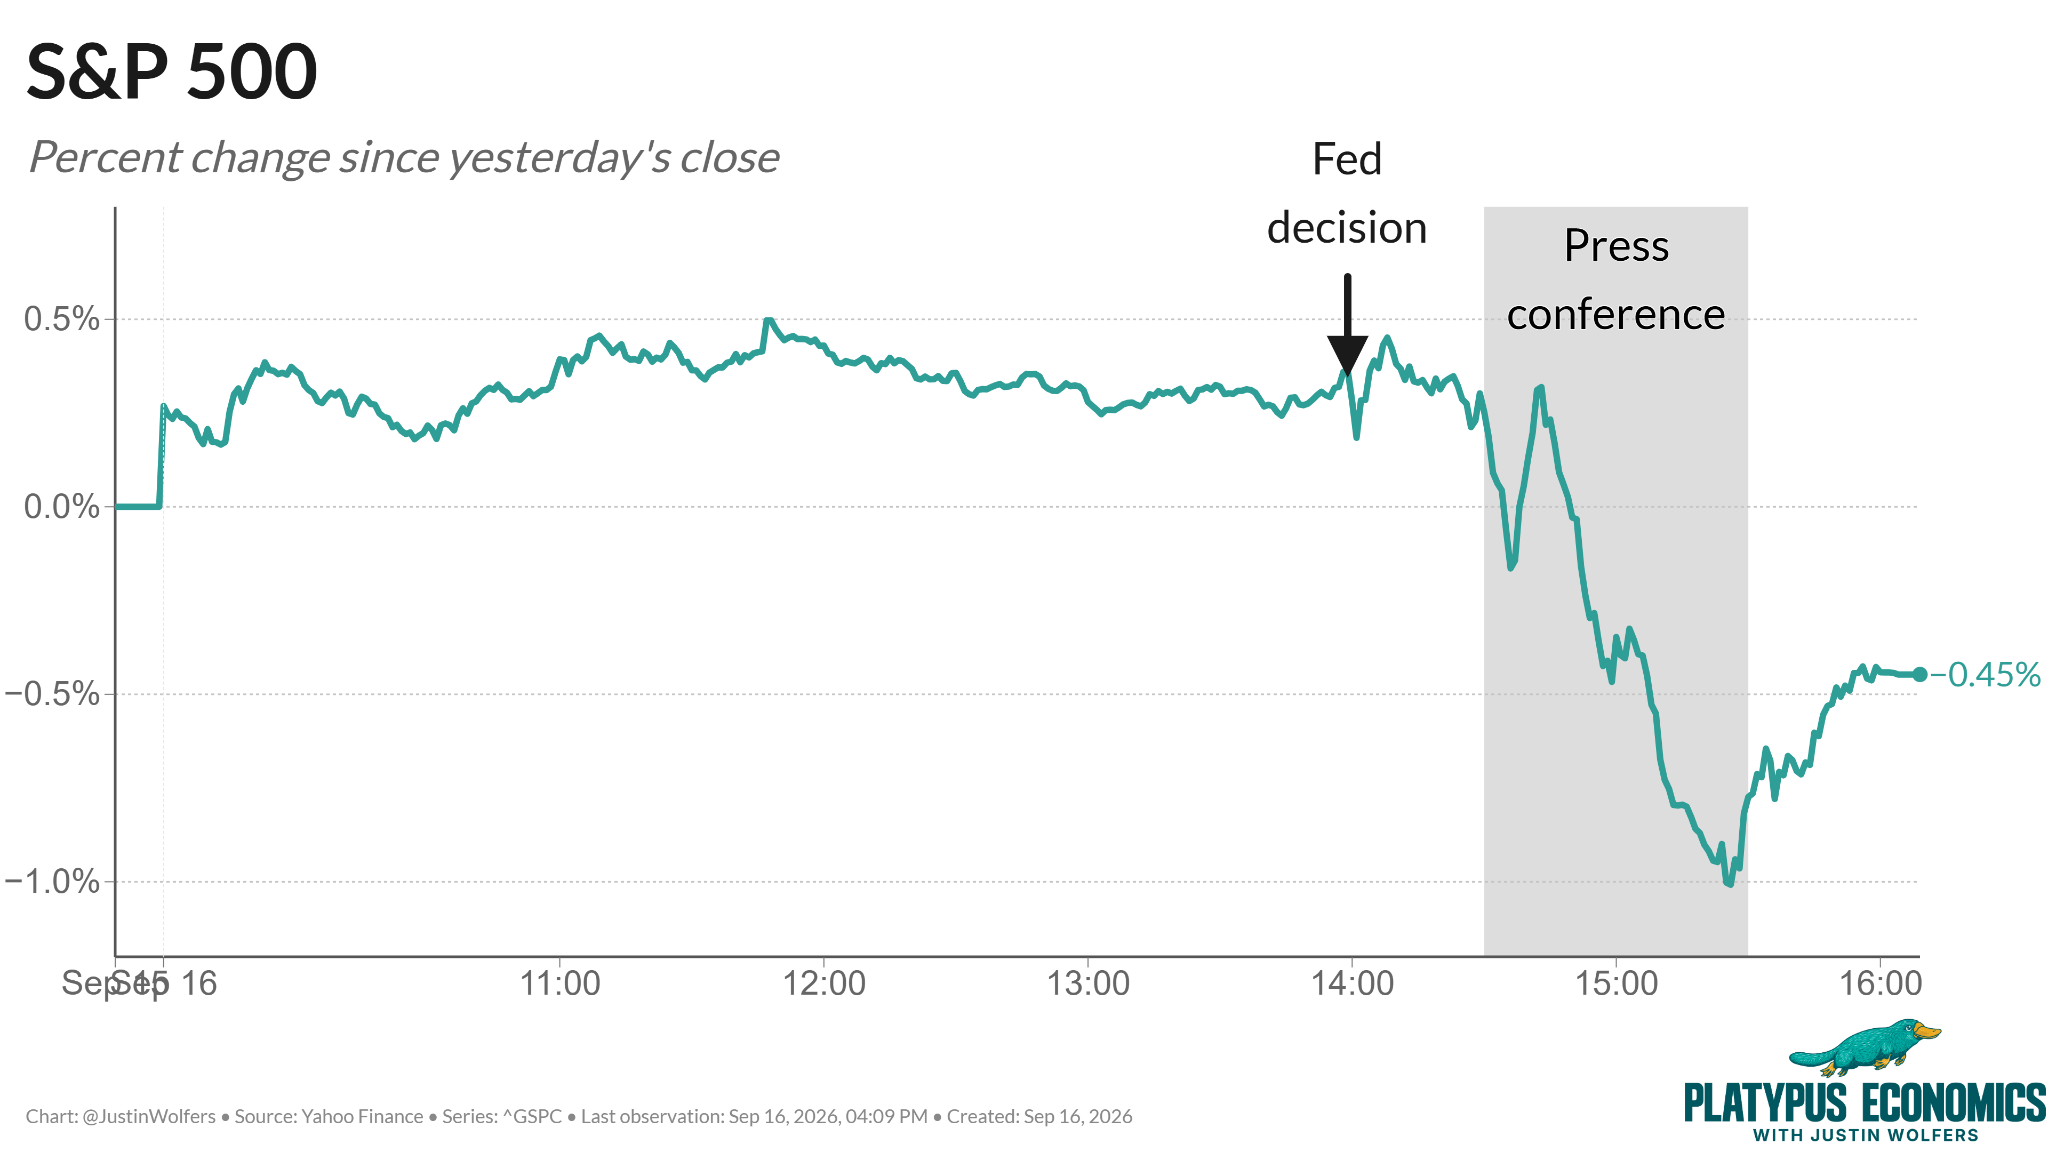
According to the markets, the most important economic news of the day wasn’t what the Fed did. It was what Kevin said.
Why would markets react like that? Beige Kevin is boring. Nobody sells stocks because a boring economist said boring things. What investors seemed to realize is that the Fed is now run by someone willing to take real risks with the economy in order to knock out inflation. This is somewhat speculative, but I reckon markets were tipping their hat to recognize that the new Fed chair is Hawkish Kevin.
So a word to Silent Kevin: Whether you like it or not, folks are listening to what you say. So be as clear as you possibly can. And, to be fair, he might say he was. His message today was that inflation is too high and Hawkish Kevin has had enough. Markets heard him.
The future(s)
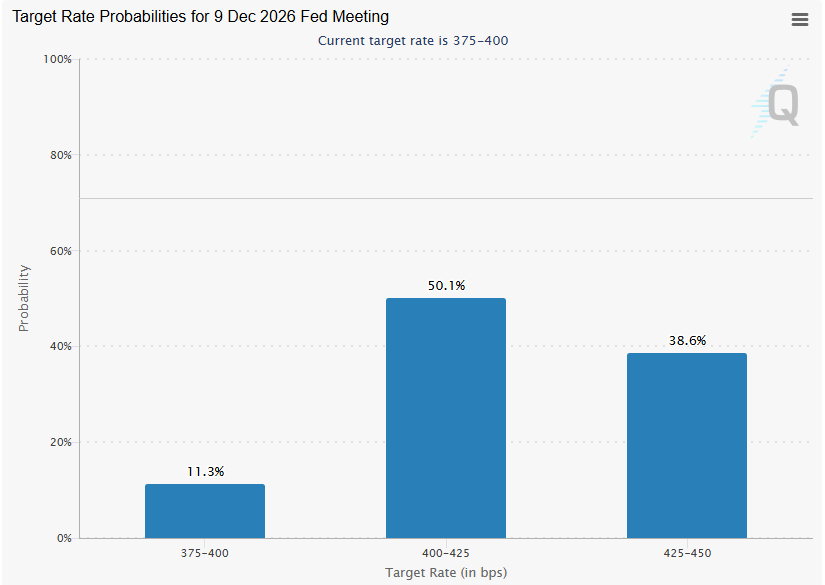
Silent Kevin won’t tell you what the Fed does next, but markets are happy to guess.
Futures markets put roughly 50-50 odds on another hike at the very next meeting, in October. The Fed might prefer to wait. Remember, the last time they did this was 2023. If they hold again, they could get out of a political bind: The midterms are in November, and I suspect the committee would feel uncomfortable raising rates just before an election.
Look out to December, and futures put the odds of at least one more hike by year’s end at roughly 90%. There’s a very real chance of two. The rest of the committee, unlike Silent Kevin, was pretty clear. Their projections show more hikes are coming.
The elephant in the other room
I can’t fail to mention the president here. He didn’t get a vote today, but he sure made a lot of noise. In fact, he bellowed like an elephant.
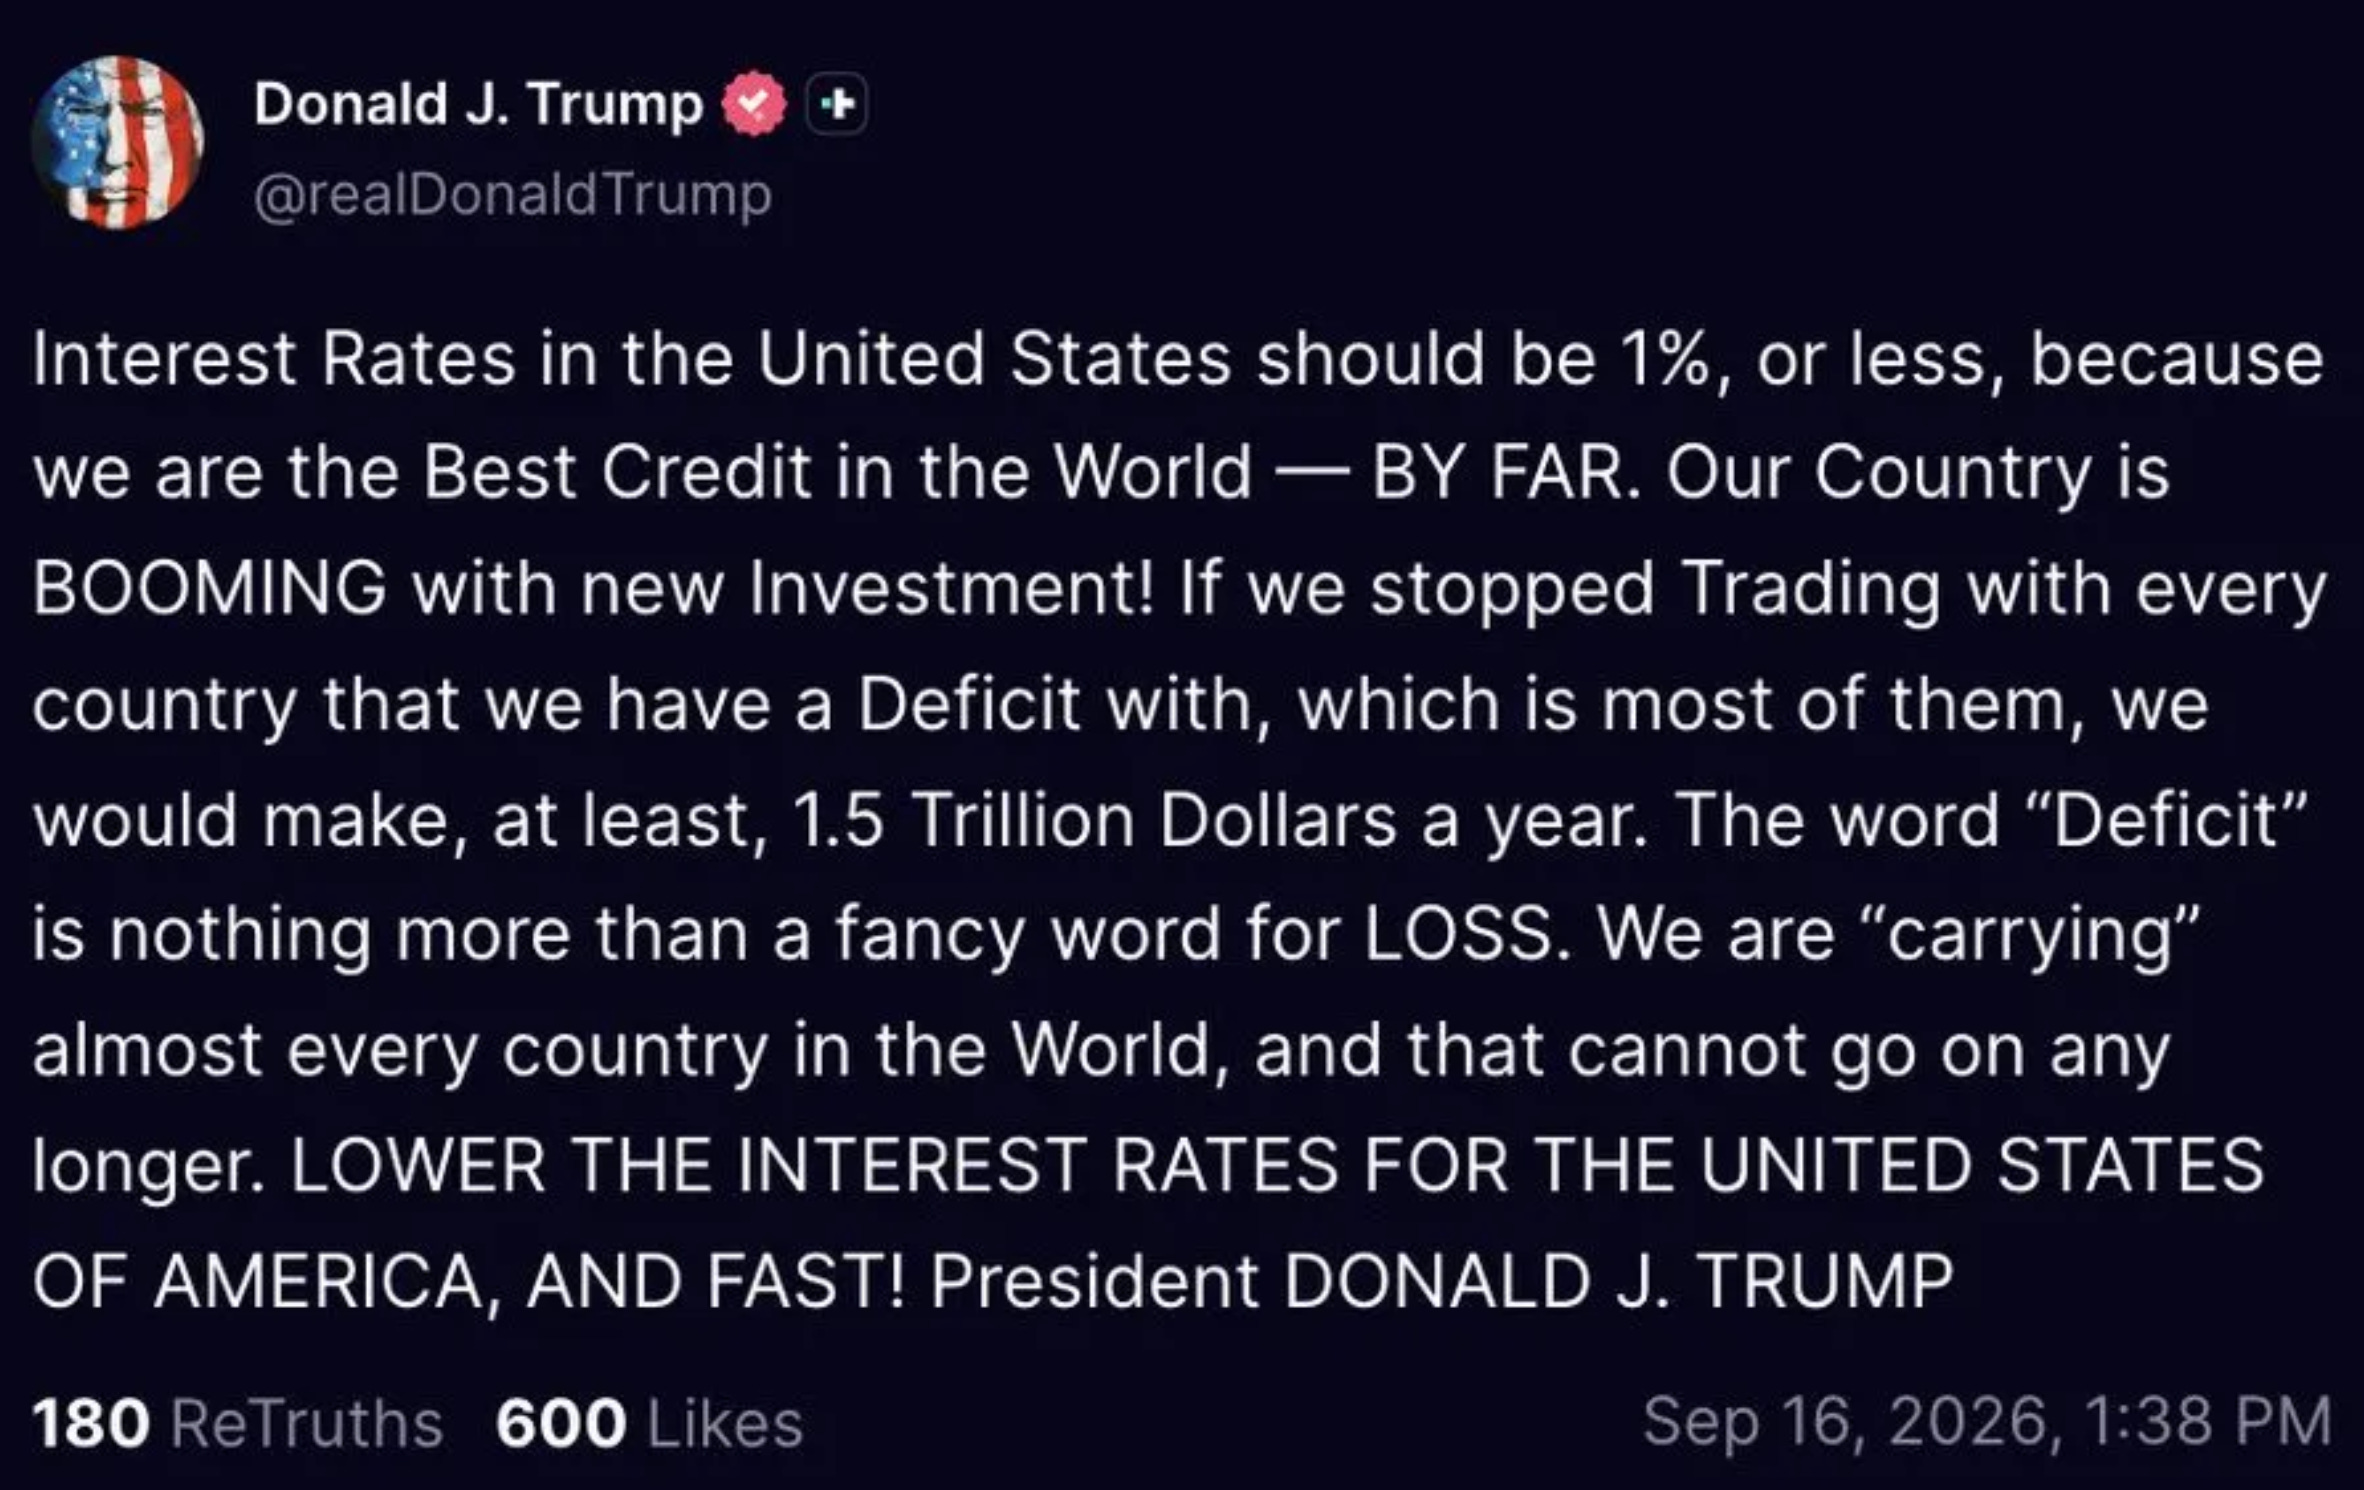
A couple of weeks ago, he posted on social media that if the Fed didn’t lower rates, he’d stop trading with countries America runs a trade deficit with. This week, he doubled down and said he meant it.


If you’re thinking, “Gosh, my understanding of economics doesn’t give me any insight into how those things are related…” then let me reassure you that the problem is not you. The president was essentially threatening to do something really bizarre unless the Fed did what he wanted.
And today, Kevin Warsh called his bluff.
My fervent hope is that the president didn’t mean it. There’s no reason to cut off trade with another country because a bloke you appointed made a decision within America that shapes the American economy based on American data.
All 12 voting members of the committee supported this hike, including officials appointed by presidents of both parties. As far as I can tell, the only person who thinks rates should be lower is the White House, and I suspect that says more about politics than about the state of the economy.
The right call on a nervous morning
If I were Kevin Warsh, I would have woken up this morning nervous. He had two options, and both were rough.
He could do what markets expected, raise rates, and earn the ire of the White House. Which he has done.
Or he could do what the president wanted, and he would have revealed himself as Sock Puppet Kevin. Perhaps that wouldn’t have led to a crash out at 1600 Pennsylvania Avenue, but I reckon it would have caused one on Wall Street.
He raised rates. It was the right decision.
He’s not a sock puppet. But he’s also not nearly as silent as he thinks.
Someone doing the right thing? Maybe it will catch on!
Good recap. Can’t wait for next episode of All My Kevins 📉📈💸